Menu
The tax authorities explained the change in the procedure for paying excise duties on alcoholic products from January 1, 2027.
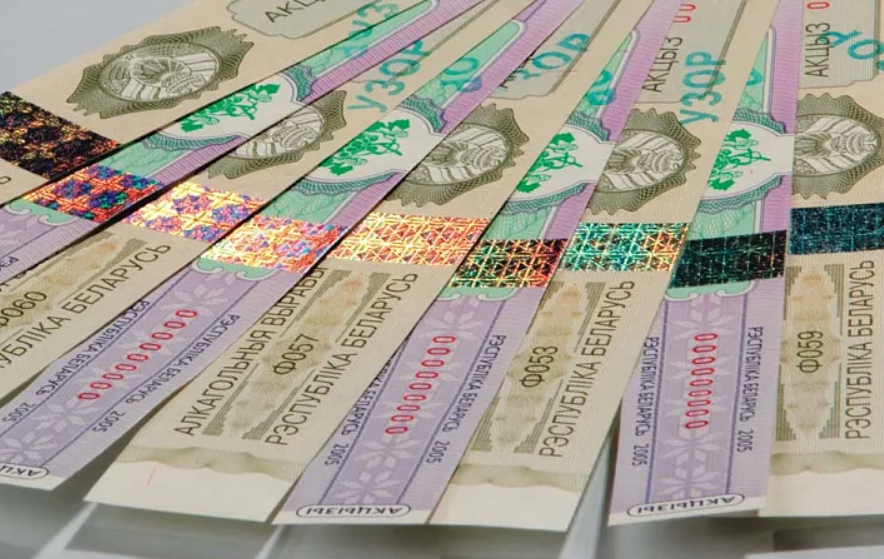
Attention to taxpayers engaged in the production of alcoholic products, low‑alcohol drinks with an alcohol content of more than 1.2 % and less than 7 % (low‑alcohol natural drinks, other low‑alcohol drinks), ciders (except fruit‑berry ciders) and/or beer, beer cocktails, drinks made on the basis of beer (beer drinks) (hereinafter – alcoholic products, low‑alcohol drinks and beer).
Regarding the above-mentioned excisable goods shipped from 1 January 2027:
- The moment of actual sale (transfer) will be determined as the day of their shipment (transfer) falling within the tax period (month), including to a separate unit of the taxpayer, i.e., “by shipment”. This means that the sale (transfer) of goods is reflected in the excise tax declaration (settlement) for the month in which the shipment occurred;
- Payment of excise duties will be made no later than the 22nd day of the third month following the expired tax period (the month of shipment).
The above provisions will affect the following groups of excisable goods:
| Group code | Group name | |------------|------------| | 14 01 | Excise on spirit from food raw material, vodka, liqueur and spirit
no later than the 22nd day of the third month following the expired tax period (for alcoholic beverages, low‑alcohol drinks, and beer shipped from January 1, 2027).
The deadline for taxpayers to submit to tax authorities the excise tax declaration (settlement) for these excisable goods remains unchanged and is no later than the 20th day of the month following the expired tax period.
In order to ensure a smooth transition to the revised method of calculating and paying excise duties on the aforementioned excisable goods, and to avoid potential problems, the Ministry of Taxes and Fees of the Republic of Belarus recommends that producers of alcoholic beverages, low‑alcohol drinks, and beer begin preparatory work and relevant organizational measures now, including:
- amending accounting policies;
- modifying contracts on supply/sales terms for the specified excisable goods;
- configuring accounting systems and software to meet the new requirements for calculating and paying excise duties.