Menu
Tax Inspectorate informs. Change in the procedure for processing and receipt of electronic documents by the tax authority.
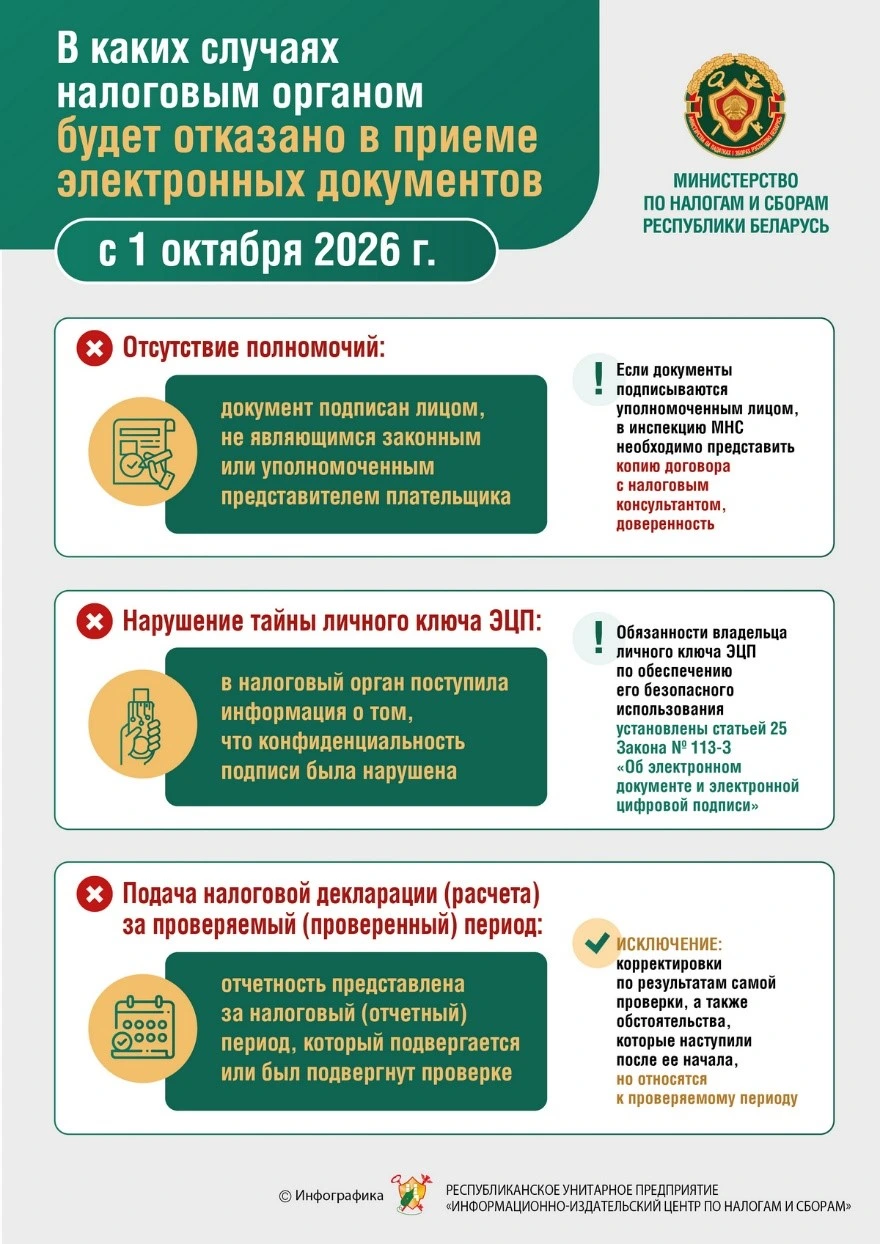
From October 1, 2026, the procedure for processing and accepting tax declarations (calculations) and other documents submitted in electronic form by the tax authority has changed, as approved by the Ministry of Taxes and Duties Resolution No. 7 dated February 29, 2012 "On Submission of Electronic Documents to Tax Authorities".
The resolution specifies the provisions regarding the acceptance (or refusal to accept) electronic documents and the procedure for notifying the taxpayer thereof.
The tax authority will refuse to accept an electronic document signed by a person who is not the taxpayer's legal or authorized representative. Such a document will not be processed further.
Article 24 of the Tax Code of the Republic of Belarus establishes that a taxpayer may participate in relations regulated by tax legislation through its legal or authorized representative. The representative's authority must be documented.
When an electronic document is signed with an electronic digital signature by the legal representative of a legal entity (director, liquidator, or manager in an insolvency or bankruptcy case), or by an individual entrepreneur, it is not necessary to confirm the authority to sign documents.
If an electronic document is signed by the taxpayer's authorized representative, a document (or its copy) confirming the authority must be submitted to the tax authority: a contract with a tax consultant; a power of attorney signed by the head of the organization or another person (for legal entities); a power of attorney certified in accordance with legislation, for example, notarized (when representing the interests of individuals, including individual entrepreneurs).
The document confirming authority is submitted to the tax authority only once, meaning it does not need to be presented with each electronic document submission, and may be submitted by any available means – in person, by mail, by courier, or electronically.
Moreover, refusal to accept an electronic document will be sent:
- if the tax authority has information received from the key holder that the confidentiality of the private key of the electronic digital signature has been compromised (the obligations of the private key holder are established by Article 25 of the Law of the Republic of Belarus of December 28, 2009 No. 113‑Z “On Electronic Document and Electronic Digital Signature”);
- in case of submission of a tax declaration (calculation) for a tax (reporting) period subject to (having undergone) audit, if this is not related to reflecting in the taxpayer's accounting or tax accounting the results of the audit or circumstances that arose after the start of the audit but pertain to the audited period. This requirement is contained in the provisions of parts four and five of paragraph 6 of article 40 of the Tax Code of the Republic of Belarus.